Blog-Details
09 Nov 2026
One of the largest investments you can make is a home. But maintaining that investment is equally crucial as buying. Fires, storms, theft, and accidents are all unexpected events that can lead to great financial loss. This is where homeowners insurance comes in handy. It offers financial coverage for covered damages, losses and some liabilities of your property.
As a first-time homeowner, it is important to be aware of your coverage options so you can make informed decisions. Homeowners insurance is a guide for beginners that details what it is, what it covers, and why it is important for homeowners to have the right policy.
Homeowners insurance is a question asked by many new homeowners: what is home insurance, and why do they need it? Homeowners insurance is a form of property insurance designed to help safeguard your home, belongings, and financial assets from certain covered perils.
An insurance company is the one that you pay a premium to when you buy a policy. The insurer, in turn, will cover property damage or loss in the event of covered incidents.
A typical homeowners insurance policy can cover you for:
Coverage is subject to your policy terms, exclusions, limits and deductibles.
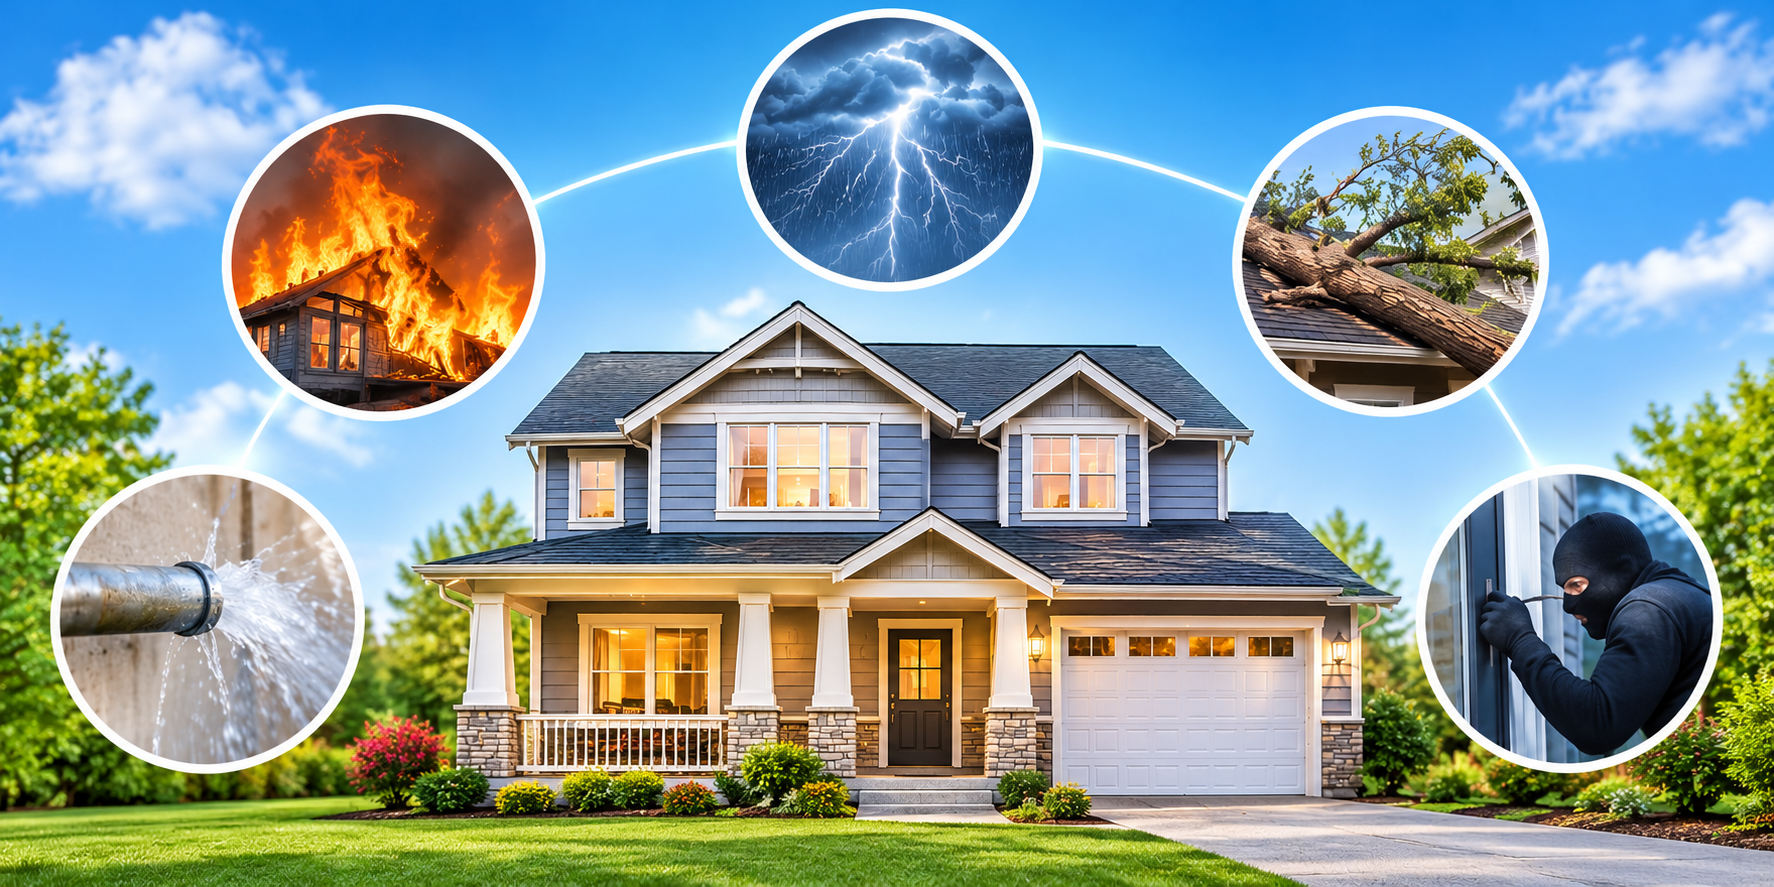
Once you know what home insurance is, you can find the coverage that your home requires. There are a number of important coverage categories that are found in most standard homeowners policies.
Dwelling coverage is used to help cover the physical structure of your home if it sustains covered damage. This can involve walls, roofs, floors, ceilings, and any permanently attached fixtures. The dwelling coverage amount should be based on the estimated cost to rebuild your home, not its current market value.
There are valuable items in your home, such as furniture, electronics, clothing, appliances, and other personal items.
Personal property coverage provides protection for these items to replace or repair them if they are damaged or lost due to covered events. Some items of value may need special coverage.
Things can go wrong at any moment. For example, a visitor might get injured after slipping on your property.
Personal liability coverage may cover legal, settlement and medical expenses if you are held legally liable for another person’s injuries or property damage.
Suppose your house is temporarily uninhabitable due to a fire. While repairs are being made, you may need to find a hotel or rent a different place to stay.
Additional living expenses coverage may be used to help cover eligible temporary housing and related expenses up to the policy limit.
Your property can have buildings that are detached from your home. These may include garages, fences, sheds and some outdoor buildings.
Other structures’ coverage helps protect these buildings against covered damages.
While homeowners insurance offers great protection, it doesn’t protect against all scenarios. Knowing what is excluded can help you avoid financial surprises.
Depending on your policy, common exclusions may include:
Some exclusions may be covered by a separate policy or other endorsements. For instance, homeowners might require separate flood or earthquake insurance. Always check your policy documents to see what is covered and what is not covered.
There are a number of factors in determining the proper coverage. The type of insurance you need depends on the structure of your home, where it’s located, the replacement value, and your belongings.
Here are some key factors to take into account when choosing coverage:
An insurance professional will be able to assess your situation and suggest appropriate coverage.
The cost of homeowners insurance varies from house to house and company to company. There are a number of factors that affect the cost.
These include:
When you compare several insurance quotes, you will be able to get a better understanding of what is available. But the lowest price is not the only factor to consider when deciding on your policy. Ensure that the coverage is sufficient to meet your needs.
Finding suitable coverage becomes easier when you understand your priorities.
Here are some tips for beginners:
These measures can help you select protection that will benefit your financial security.
Protect your home and everything you value with the right insurance coverage. Contact Warren Insurance Agency today to explore homeowners insurance options and find a policy that fits your property and protection needs.
© 2026 Warren Insurance Agency. All Rights Reserved
Crafted with Love: DigiCorns